Deal teardown 01 · Rent stress test
Rental-Income Stress Test: Two Fixed-Debt Examples
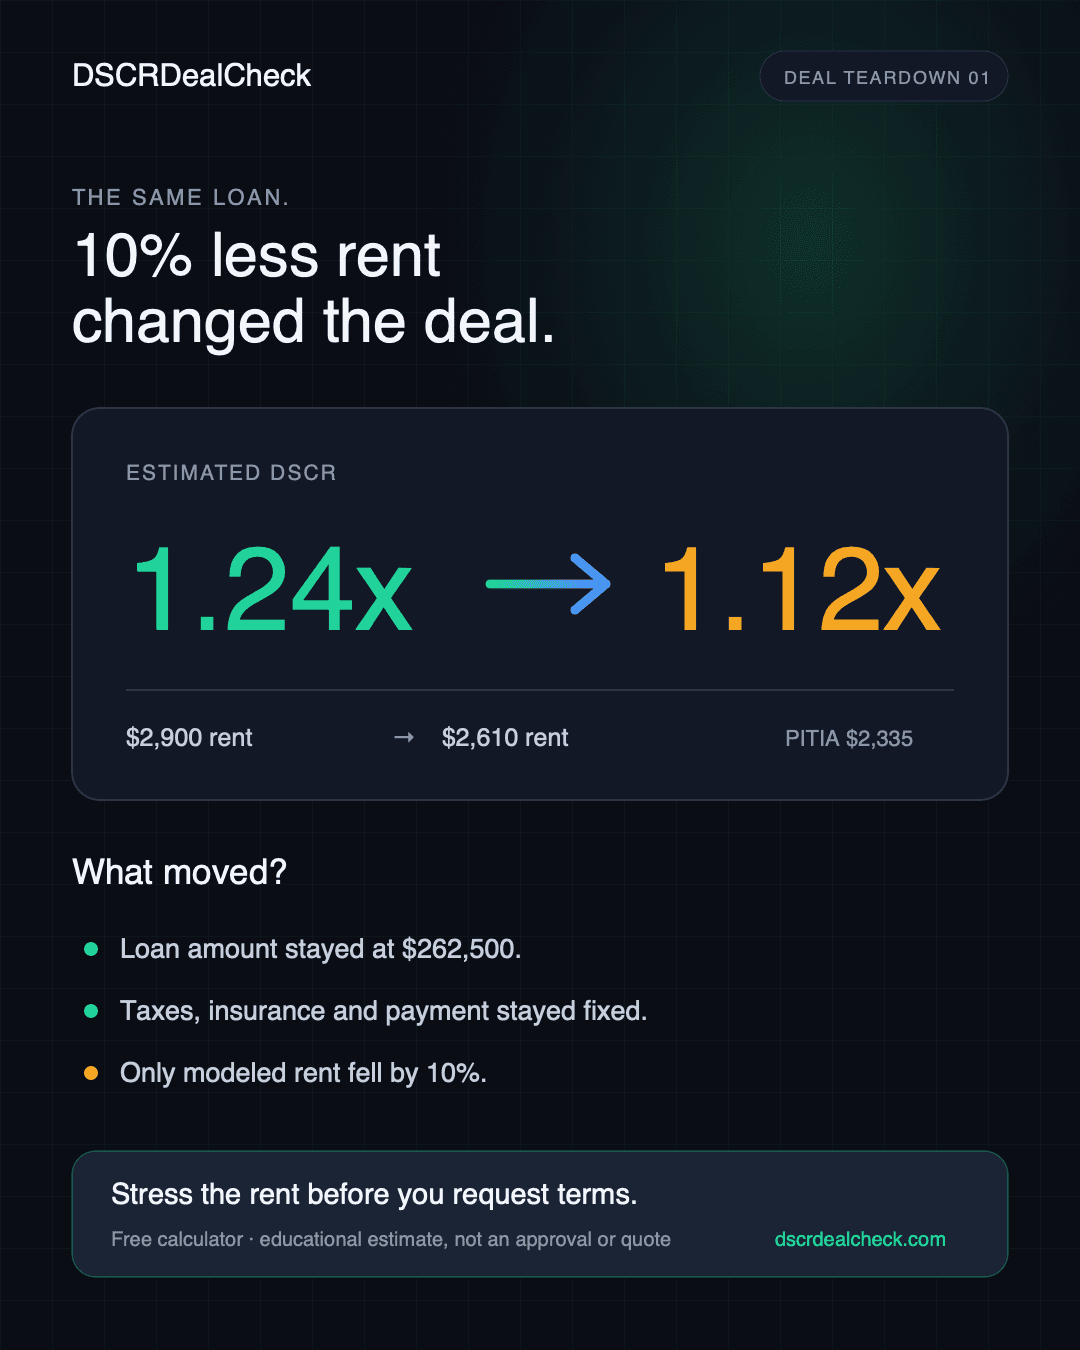
The original 10% example shows DSCR moving from 1.24 to 1.12. The new 20% example takes rent from $3,000 to $2,400 and DSCR from 1.20 to 0.96. Both hold debt fixed and use fictional figures.
Published · Educational scenario
Updated · Fictional examples
Jump to the $3,000 → $2,400 example ↓New worked example · fictional figures
Rent falls from $3,000 to $2,400. DSCR moves from 1.20 to 0.96.
Only rent changes in this 20% downside scenario. The loan balance, rate, term and modeled monthly payment stay fixed, as do taxes, insurance and HOA. Lower rent leaves $600 less each month to cover that same PITIA.
Open the rent comparator →Monthly rent
- Base
- $3,000.00
- Adverse
- $2,400.00
- Change
- -$600.00
Monthly PITIA
- Base
- $2,507.80
- Adverse
- $2,507.80
- Change
- $0.00
DSCR
- Base
- 1.20
- Adverse
- 0.96
- Change
- -0.24
Rent minus PITIA / mo
- Base
- $492.20
- Adverse
- -$107.80
- Change
- -$600.00
Change means adverse minus base. Results come from the same calculator engine and are rounded for display.
Reproduce it in the comparator
- Open the comparator above. It may show inputs you previously saved in this browser.
- To load this fictional case, use “Reset example and clear saved inputs” at the top of the calculator. This replaces your saved calculator inputs with the example.
- In “What if rent falls?”, choose 20%. Read Base, Adverse and Change, then use “Download comparison (CSV)” to keep those exact assumptions and results.
Fixed assumptions: $400,000 property value, 70% modeled LTV and a $280,000 loan; assumed 7.5% fixed rate over 30 years; $4,800 annual property taxes, $1,800 annual insurance and $0 HOA. These are invented inputs, not current loan terms. They produce monthly PITIA of $2,507.80.
Coverage and cash flow are not net profit
DSCR divides rent by PITIA; it is a coverage ratio, not a dollar profit. Here, rent minus PITIA moves from $492.20 to -$107.80 per month. This limited cash-flow measure excludes maintenance, management, vacancy reserves, utilities, capital spending and other operating costs. Neither result measures net profit or a complete investment return.
A 0.96 DSCR means modeled rent is below this fixed PITIA. It is not a prediction of future rent, an approval decision or a loan offer. This exercise holds debt fixed; it does not calculate a new eligible loan amount.
Scenario inputs and outputs
Original 10% example: 1.24 to 1.12
- Modeled loan
- $262,500
- Baseline rent
- $2,900/mo
- Stressed rent
- $2,610/mo
- Estimated PITIA
- $2,335/mo
- Baseline DSCR
- 1.24x
- Stressed DSCR
- 1.12x
Reconciliation
Baseline
$2,900 rent ÷ $2,335 PITIA = 1.24x
10% rent stress
$2,610 rent ÷ $2,335 PITIA = 1.12x
A deal can remain above 1.00x and still lose meaningful breathing room. Stress the supportable rent before relying on a refinance, purchase, or lender-program threshold.
Only one assumption moved
The modeled loan amount, principal-and-interest payment, property taxes, insurance, HOA, and total PITIA stayed fixed. Monthly rent fell from $2,900 to $2,610. That one change reduced estimated DSCR by about 0.12x.
Why rent deserves a downside case
Asking rent is not always the same as collected rent or the amount a provider accepts. Vacancy, concessions, seasonality, appraisal market rent, lease terms, and provider calculations can create a lower usable figure.
- Run a baseline using a supportable lease or market-rent assumption.
- Run at least one lower-rent case before committing to debt service.
- Ask the provider which rent evidence and calculation will control.
- Keep repairs, vacancy, management, and capital expenditures in the investment analysis even when they are outside PITIA.
What the 1.12x result does—and does not—say
In this educational model, rent is 1.12 times estimated PITIA. It does not mean a provider will approve the loan. Credit, reserves, leverage, property eligibility, appraisal, documentation, pricing, and the provider's own DSCR method still control.
Run the same check on your deal
Compare base rent with a lower-rent scenario
Open “What if rent falls?” in the free cash-out calculator. Set the rent reduction, compare Base, Adverse and Change, and download the same comparison as a CSV. The loan and PITIA stay fixed.
No account or contact details are required to run the calculation. Results are educational estimates, not an approval, commitment, or personalized rate quote.
Frequently asked
Does a 1.12x DSCR qualify for a DSCR loan?
It depends on the provider and the complete file. Some programs publish criteria near or below 1.12x, while others require more coverage or reduce leverage. The calculator is not an approval or quote.
Why use a 10% rent stress?
It is a simple sensitivity case, not a forecast. Use a decline that reflects the property's lease, market, vacancy, concessions, seasonality, and operating plan.
What is included in PITIA here?
Estimated principal, interest, property taxes, insurance, and HOA. Operating expenses such as repairs, management, utilities, vacancy, and capital expenditures should be analyzed separately.
More from the Deal Lab
Method note: this case uses the assumptions displayed above. Real transactions may include different rent treatment, expenses, value, costs, reserves, payoff items, timing, credit, documentation, property rules, pricing, and legal requirements. Verify current written terms directly with the provider and relevant professionals.